Real Estate on the Vero Barrier Island
Housing on the Vero Beach barrier island runs from open 1950s beachside streets to full private club communities, with oceanfront and riverfront condominiums in between. Every address carries the 32963 ZIP code, a 35-foot height limit across most of the island, and coastal insurance and construction rules that shape what gets built and how it is bought.
The Vero island market is small and segmented. What you can buy depends less on price than on the kind of place you want: an open street you can walk to the village from, a gated enclave, a club community with a membership requirement, or a condominium building on the ocean or the lagoon.
This page explains how the island market is organized and what to look at before you make a decision. It is published by The Reynolds Team of Compass, who live and work on the island. It is general information, not advice on any specific property or on the value of a home.
Related: 32963 Buyers Guide · Barrier Island Neighborhoods · Gated vs open neighborhoods · Live like a local
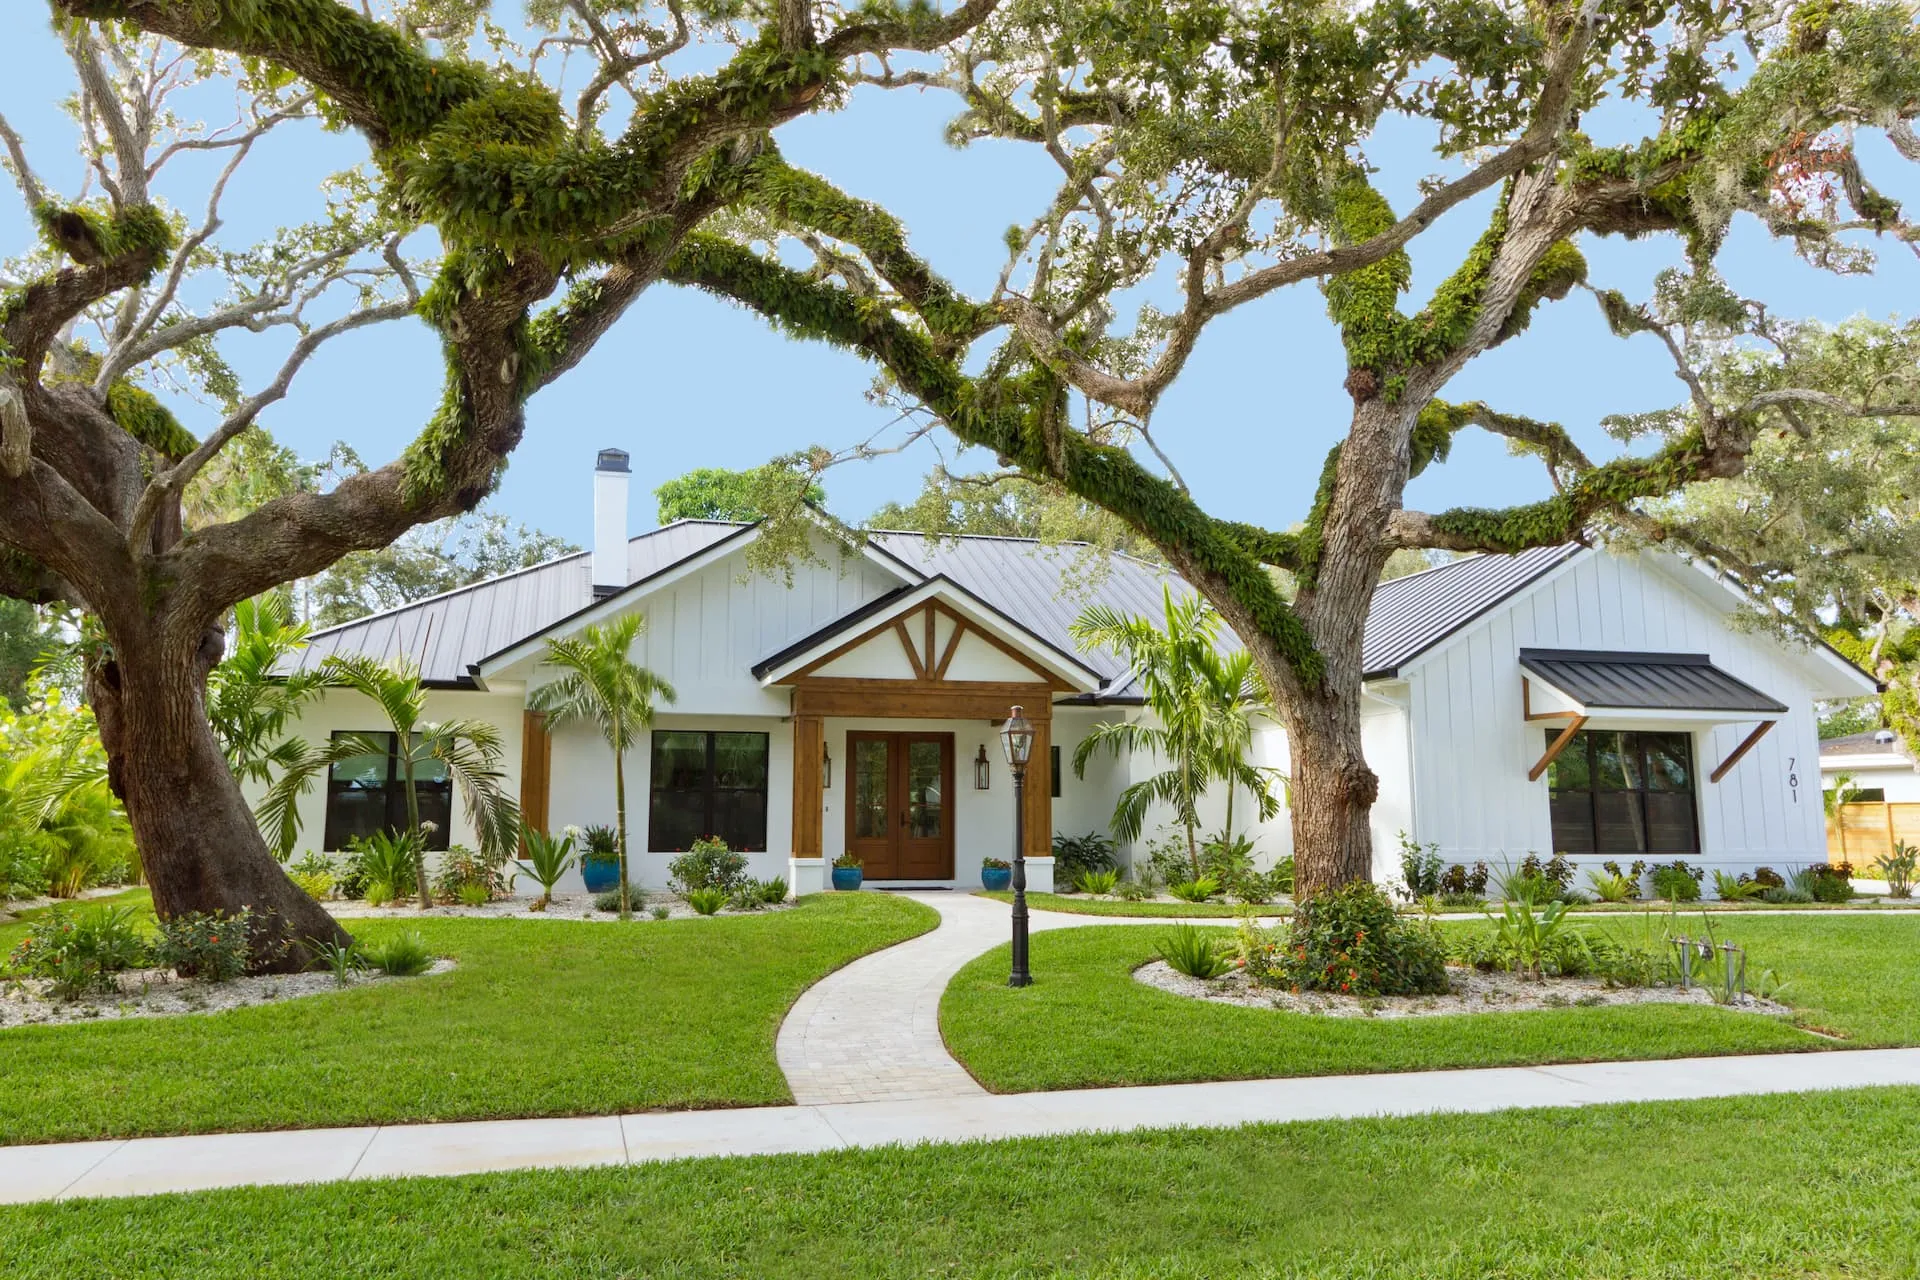
Latest on Real Estate
Quiet Luxury on Vero Beach's Barrier Island 32963
The quiet luxury lifestyle drawing buyers to Vero Beach's barrier island in 2026, and why 32963 feels different from Palm Beach and Naples.
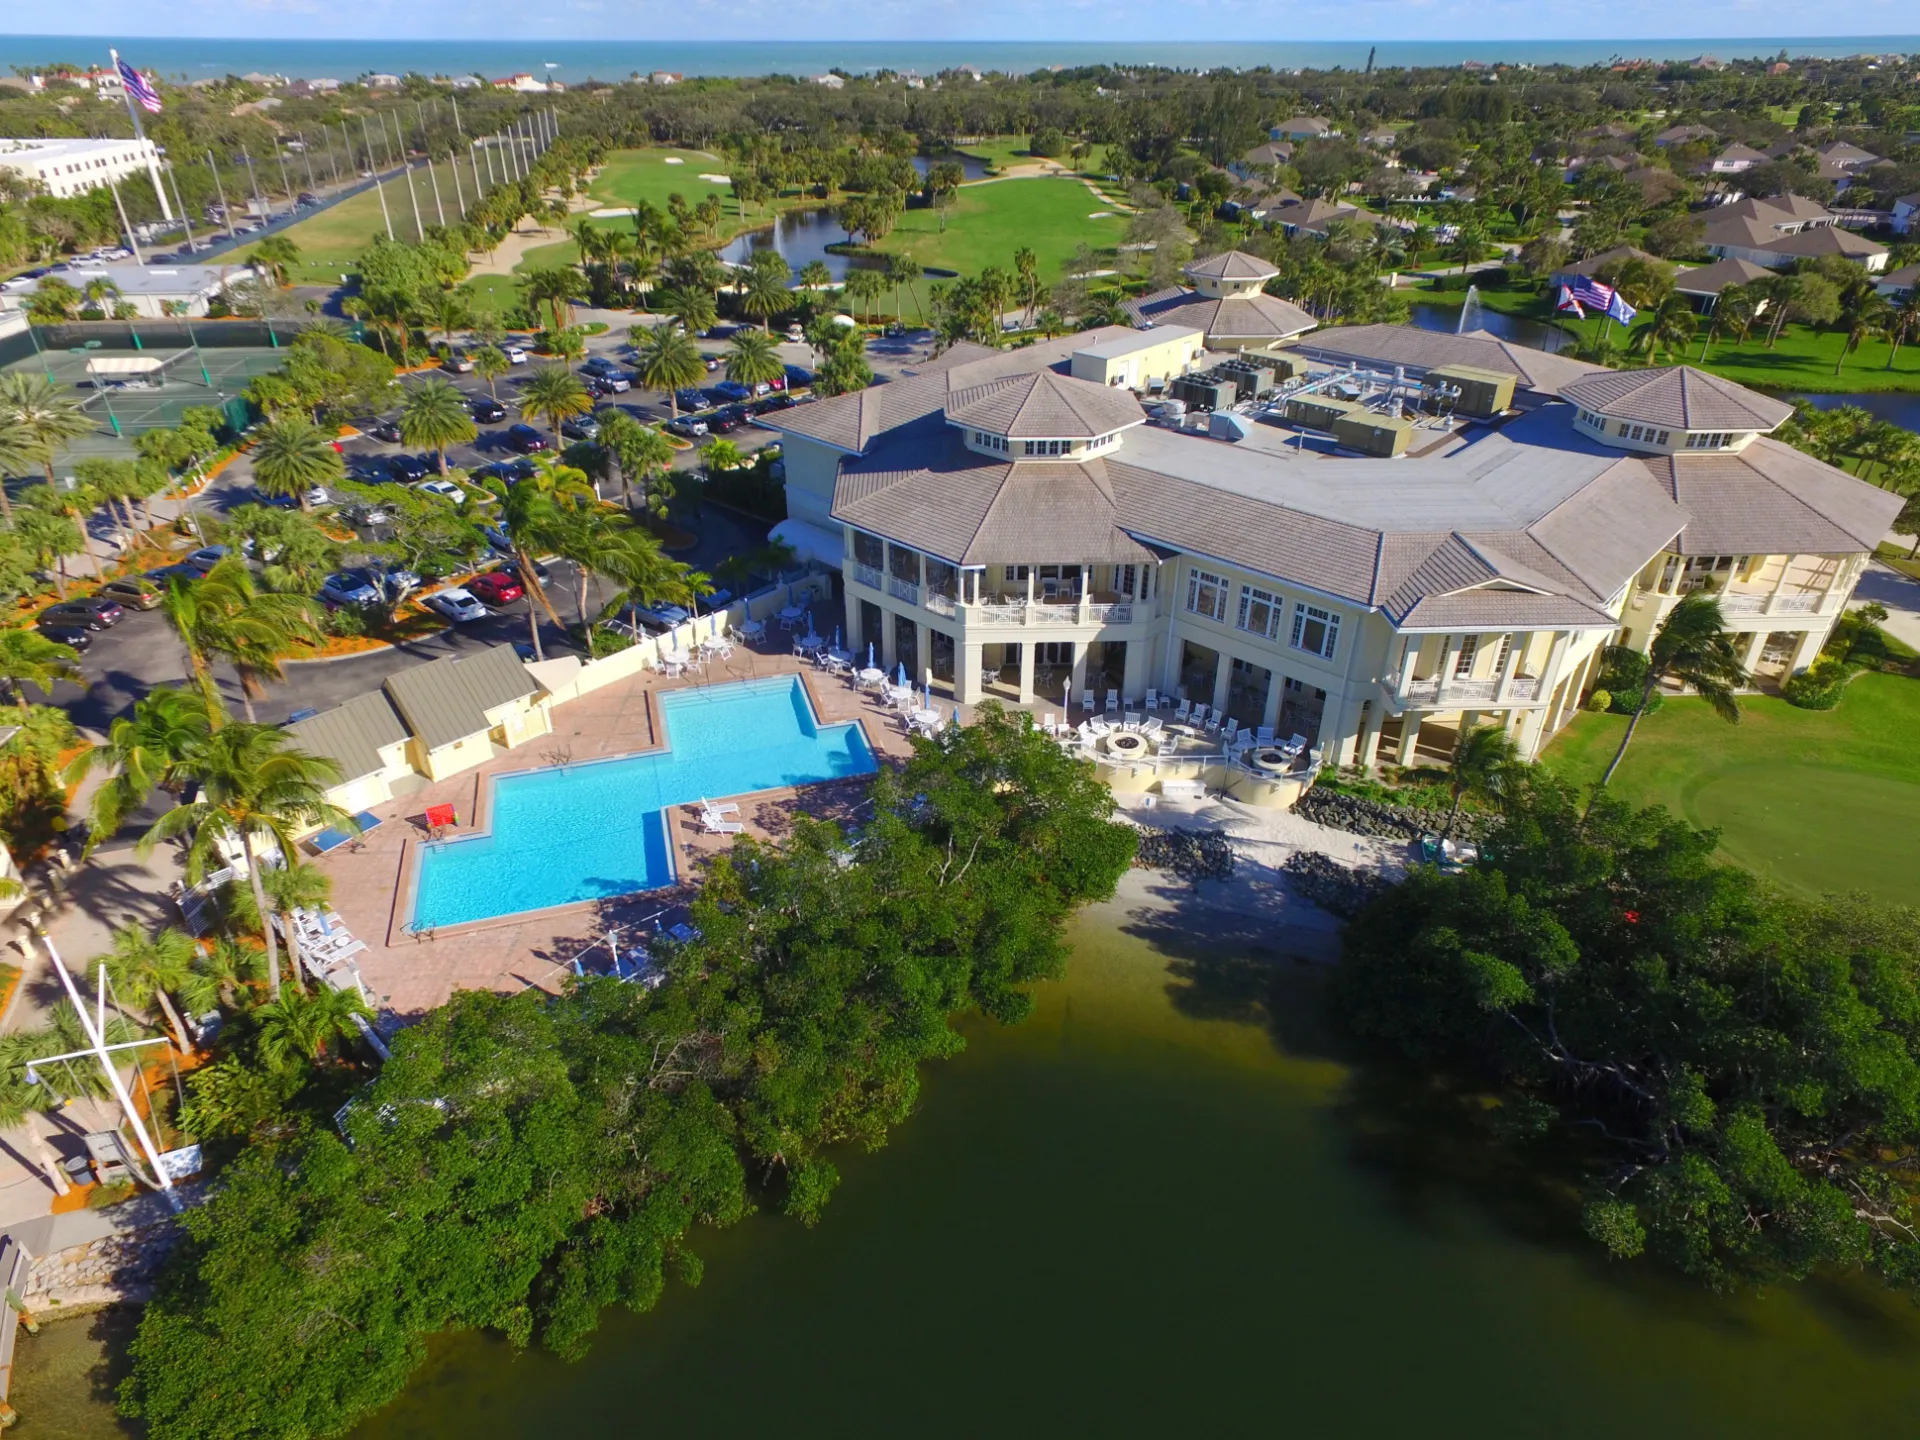
5 Things Snowbird Buyers Should Know First Before Buying a Home
Buying a seasonal home on Vero Beach's barrier island? Here are five things first-time snowbird buyers should know before making an offer in 32963.
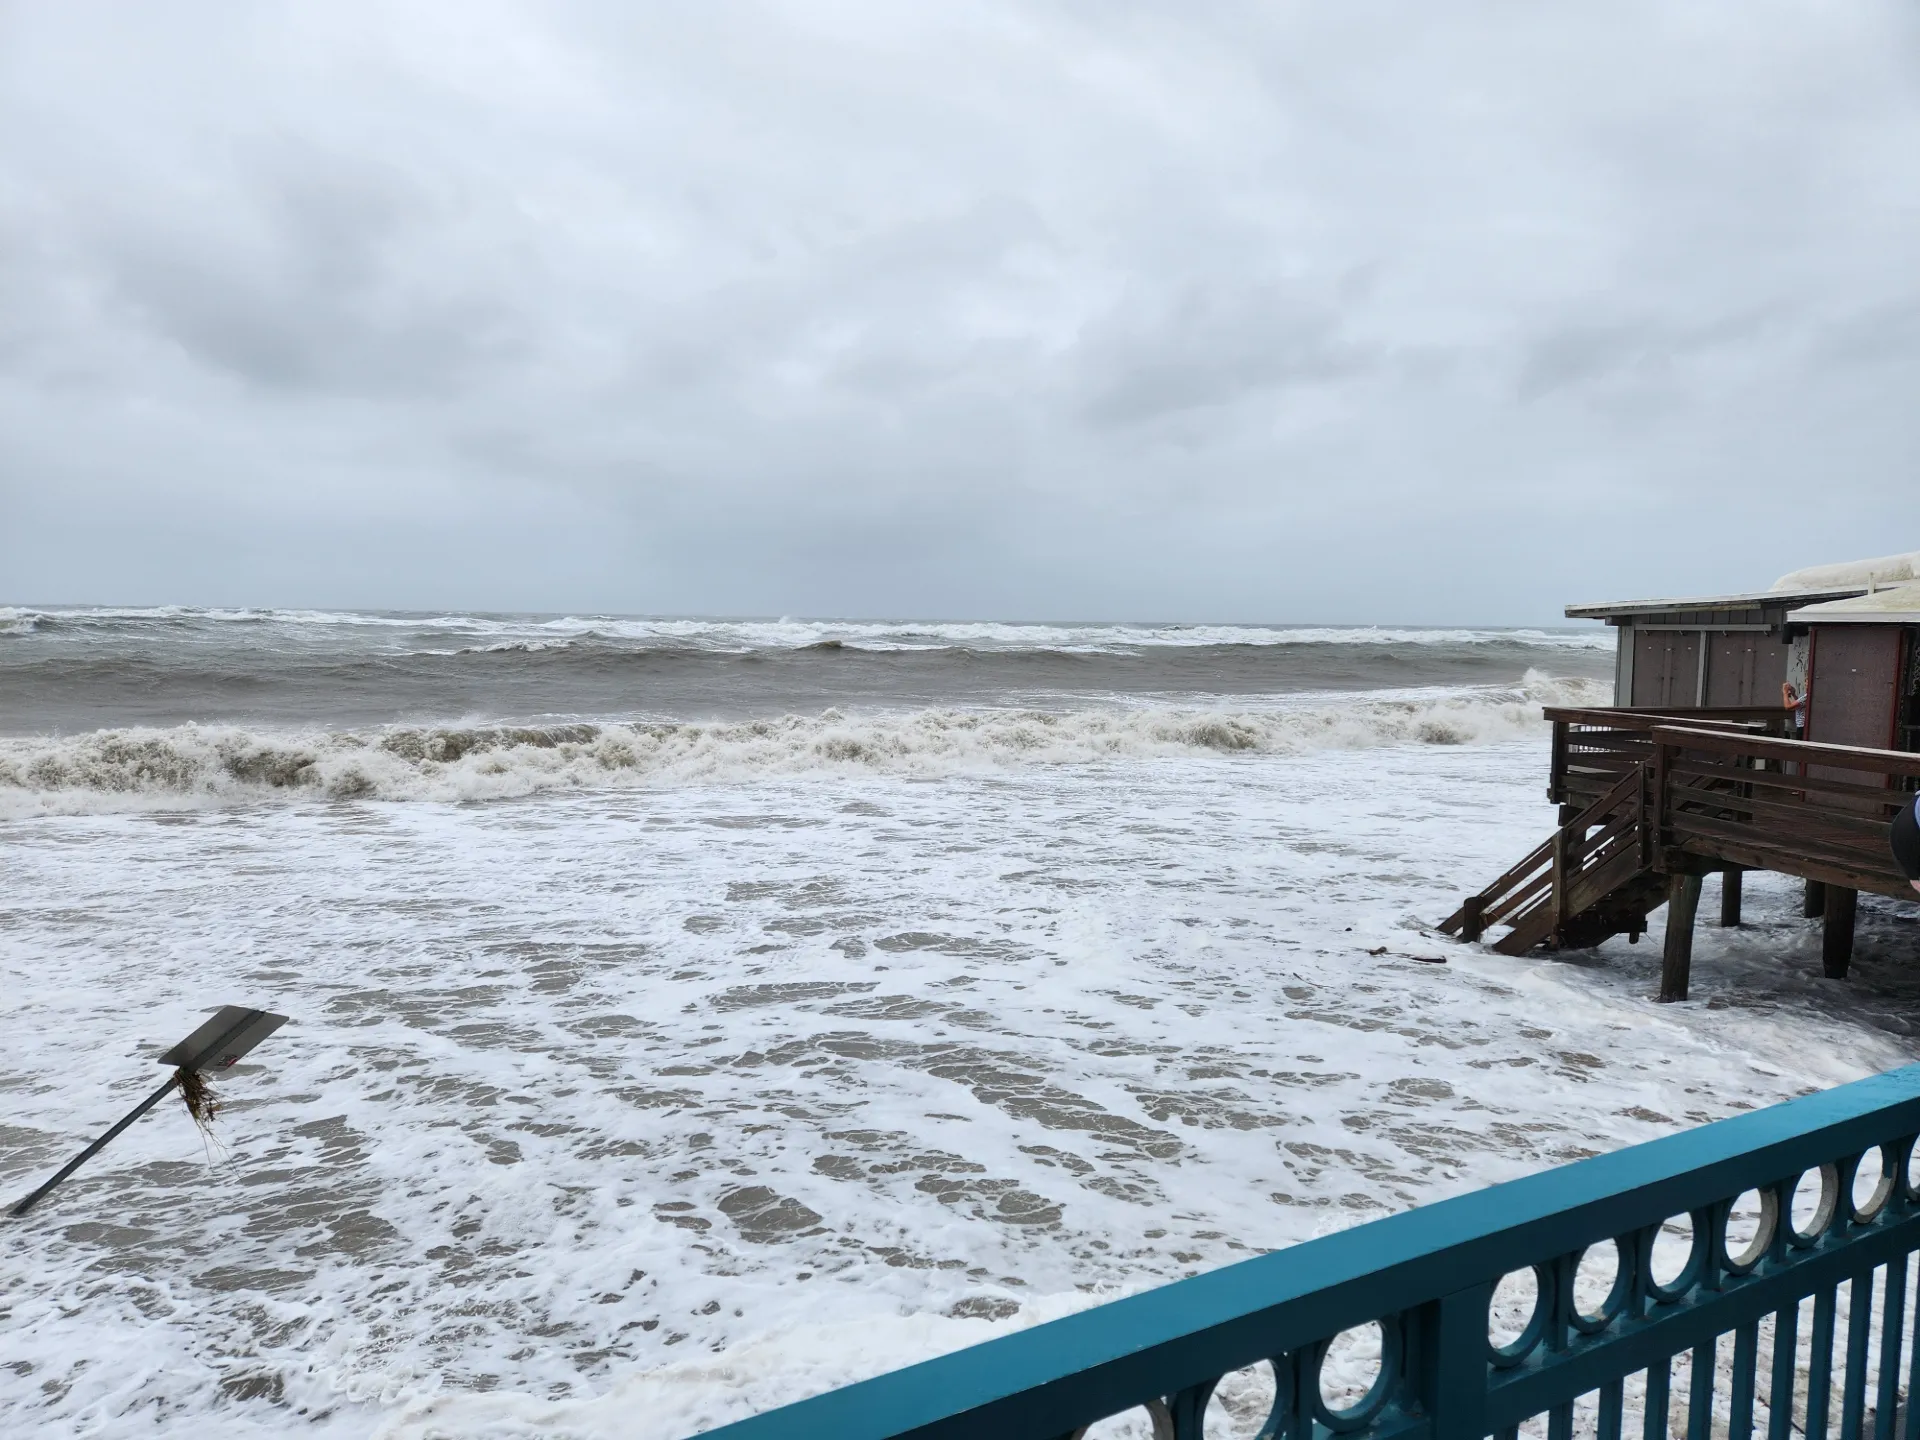
Hurricane and Insurance Reality on Vero Beach's Barrier Island
Storm risk and insurance pricing are real budget lines on the barrier island.
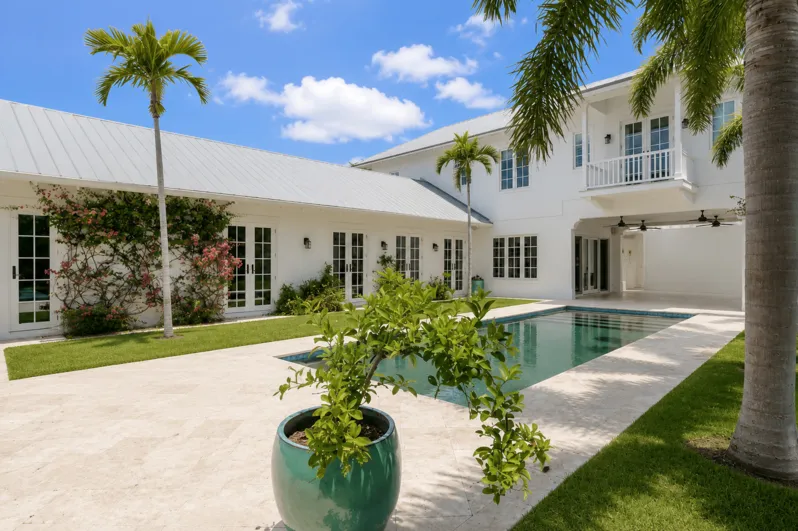
7 Reasons 32963 Is One of Florida's Best Real Estate Investments
The 32963 zip code covers Vero Beach's barrier island, and it's one of the few Florida zip codes that consistently defies statewide softening. Here's why.
Search and filter everything we have published in this section.
View allWhat Kinds of Property Are on the Island?
Four broad types: single-family homes on open beachside streets, homes inside gated neighborhoods, homes inside private club communities that require membership as a condition of ownership, and condominiums along the ocean and the Indian River Lagoon.
- 01
Open Beachside Streets
Old Riomar and other open Central Beach streets have no gate or membership requirement and are walkable to Ocean Drive.
- 02
Gated Neighborhoods
Gated neighborhoods have an HOA with its own rules on rentals, pets and exterior changes.
- 03
Private Club Communities
John's Island, Windsor, Orchid Island and Sea Oaks, where a club membership comes with the address.
- 04
Condominiums
Oceanfront and riverfront buildings, several of which predate the current height rules and stand taller than anything built today.
What Is Different About Buying on a Barrier Island?
Coastal rules and costs drive most of the differences. Windstorm and flood coverage are priced separately from a standard policy, elevation and flood zone vary block to block, and building height is capped at 35 feet across most of the island; the exceptions are multi-family zones in Indian River Shores, which allow up to 40 feet, and a few older buildings that predate the rules. Condominium buyers should also review reserves, structural reporting and any pending assessments.
The island is also entirely within the first hurricane evacuation zone, which shapes shutter, generator and evacuation planning more than day-to-day life. Insurance pricing is driven by flood zone, elevation and the home's wind mitigation features.
How Does the Season Affect the Market?
Activity follows the same November-to-April calendar as everything else on the island. Most buyers visit in season, so listings and showings concentrate there, and the summer months are quieter on both sides.
- 01
Verify the Details
Flood zone, elevation, HOA rules and membership requirements are address-specific, so confirm each one in writing.
- 02
Budget for Insurance
Wind, flood and standard coverage are separate line items on the island.
- 03
Ask About Membership
In club communities, membership is a condition of ownership and carries its own initiation and dues.
What's Your Home Worth?
Get a free, instant home valuation for your barrier island property.
Do You Need a Club Membership to Live on the Island?
No. Four island communities require club membership as a condition of ownership: John's Island, Windsor, Orchid Island and Sea Oaks. Everywhere else, including Riomar, club membership is optional or not offered.
What Should You Check Before Buying on the Island?
Flood zone and elevation for the specific address, wind and flood insurance quotes, HOA or club documents including rental rules, and for condominiums the reserves, structural reporting and any pending assessments. All of these vary address by address on the island.
How Do Hurricane Insurance Costs, Flood Zones and Wind Mitigation Work on the Island?
There is no single island-wide hurricane insurance cost. Pricing varies by the specific home's flood zone, elevation, replacement cost, construction year and wind mitigation features. Windstorm and flood coverage are separate from standard homeowners coverage, and flood zones can change from one block to the next. Buyers should obtain address-specific quotes, review the elevation certificate and commission a current wind mitigation inspection before making a decision.